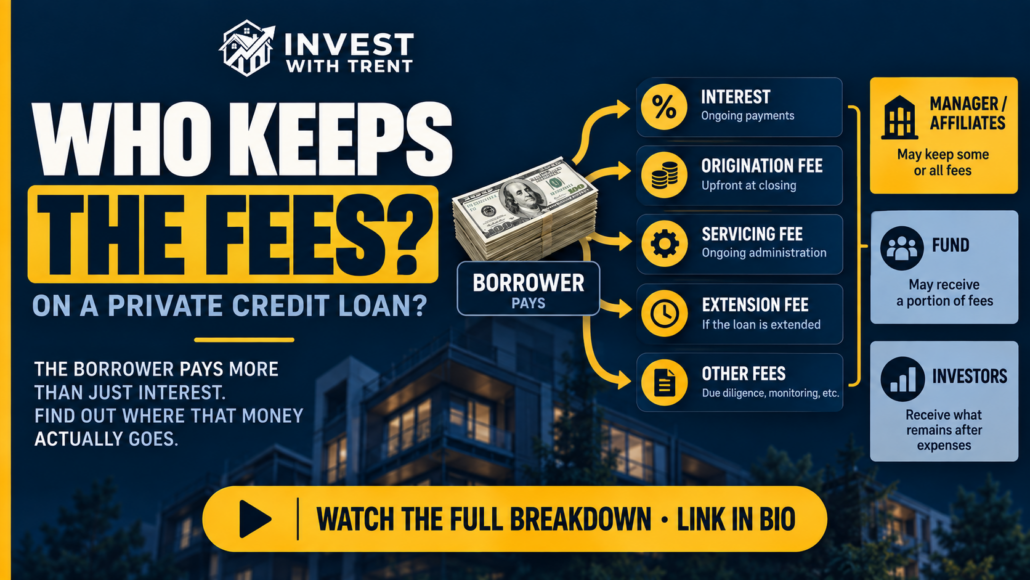
The rate a borrower pays is only one source of revenue from a private loan. Origination, servicing, extension, and other transaction fees can also matter.
Before comparing investor returns, find out who is entitled to that fee income.
Borrower interest is not total loan revenue
Interest accrues under the loan’s terms. Fees may be charged when a loan closes, is serviced, or is extended. The amount and timing depend on the transaction.
Two funds could make loans with similar interest rates and report different economics if one fund receives those fees while an affiliate of the other manager retains them.
Allocation is a document question
A manager’s explanation is a starting point. The fund’s offering and governing documents should show which entities may collect each fee, whether fees are shared with investors, and which expenses are charged against the fund.
“Fees flow to the fund” is meaningful only when the categories and exceptions are clear.
Timing changes the comparison
An origination fee might be earned near closing while loan principal is advanced later. That can lift a period’s return on capital actually deployed.
It does not mean every future loan will produce the same fee income or that a strong short-term result is a sustainable annual return. The timing of cash flows matters.
Compare what investors keep
Look beyond the borrower’s rate and the fund’s headline return. Identify gross interest, transaction fees, management and other expenses, and the net result to investors.
Then ask whether the apparent return comes from recurring loan income, deal-specific fees, borrowing, or a combination. Each has different implications for repeatability and risk.
The most useful return figure is one you can trace from the borrower’s payments through the fund’s documents to the investor’s account.