A real estate private credit fund can underwrite every individual loan conservatively and still create unnecessary risk at the portfolio level.
That happens when too much of the fund is exposed to the same borrower, property type, geographic market, or economic event.
This is why investors should evaluate more than the quality of a fund’s average loan. They should also examine how those loans fit together.
The complete list of loans held by a fund is commonly called its “loan tape.” A properly diversified loan tape helps ensure that one unsuccessful project does not become a fund-level problem.
The Number Of Loans Does Not Tell You Enough
A fund with 50 loans may sound more diversified than a fund with 20.
But the number alone can be misleading.
Suppose 30 of those 50 loans finance condominium inventory in South Florida. A decline in that market could affect many borrowers at the same time. The fund owns numerous loans, but much of the collateral is exposed to the same economic conditions.
The same problem can occur if several loans were made to related borrowers, depend on the same local employer, mature during the same quarter, or require refinancing from the same group of banks.
True diversification is not simply owning more loans. It is limiting the number of loans that can be damaged by the same event.
Loan Size Determines How Much One Mistake Can Hurt
The most obvious form of concentration is allowing a single loan to represent too much of the fund.
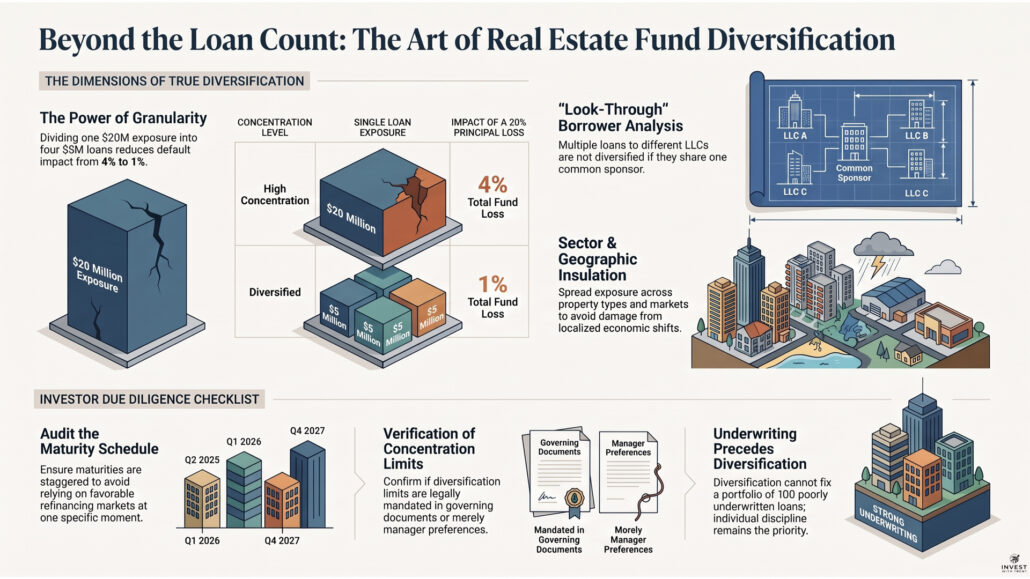
Consider a $100 million fund with a $20 million loan. If that loan suffers a 20% principal loss, the loss equals $4 million—or 4% of the entire fund.
If the same $20 million exposure were divided among four unrelated $5 million loans and one experienced the same percentage loss, the effect on the fund would be approximately 1%.
Diversification does not prevent defaults. It limits how much damage any one default can cause.
Investors should therefore ask about the fund’s maximum loan size, both in dollars and as a percentage of net assets. They should also determine whether that limit is established in the governing documents or merely represents the manager’s current preference.
Borrower Diversification Is Easy To Overlook
A loan tape can contain multiple properties while remaining concentrated in one borrower or sponsor.
For example, a developer may have separate loans on an apartment project, a condominium development, and an industrial property. Legally, those may be three different borrowing entities. Economically, however, all three could depend on the same sponsor’s liquidity, judgment, and ability to complete the projects.
If that sponsor experiences financial difficulty, several apparently unrelated loans may deteriorate together.
A thoughtful concentration analysis looks through the individual LLCs to identify common ownership, guarantors, operating partners, and sources of repayment.
Ten loans to ten separate LLCs are not meaningfully diversified if the same person controls every LLC.
Geographic Diversification Protects Against Localized Problems
Real estate is intensely local.
A city can lose a major employer. A state can experience a sharp increase in insurance premiums. A municipality can change zoning rules, impose new rent restrictions, or delay permits. A regional bank failure can reduce refinancing options for borrowers throughout one market.
A nationally diversified portfolio reduces the likelihood that one local event will affect a large percentage of the loan tape.
But geographic diversification should not become indiscriminate geographic expansion. Lending in unfamiliar markets can create its own risks if the manager lacks reliable local data, relationships, or workout capabilities.
The goal is not to place a loan in every state. It is to avoid allowing one market to determine the performance of the entire fund while remaining inside markets the manager understands.
Property-Type Diversification Reduces Sector Risk
Apartments, industrial buildings, hotels, offices, retail properties, land developments, and residential construction projects do not respond to economic conditions in the same way.
A decline in business travel may damage hotels while leaving apartments largely unaffected. Remote work can weaken office demand without materially changing demand for self-storage. Rising mortgage rates may slow home sales while increasing the number of households that continue renting.
Spreading exposure across property types can reduce dependence on one sector.
However, a fund should not diversify into property types it does not understand merely to make the loan tape look balanced. A manager with deep expertise in three sectors may be safer than one making occasional loans across ten.
Diversification should complement underwriting competence, not substitute for it.
Loan Vintage And Maturity Also Matter
Two loans secured by similar properties can carry different risks if they were originated at different points in the market cycle.
Loans originated during periods of aggressive valuations may have less protection than loans made after prices have corrected and underwriting standards have tightened.
Maturity concentration matters as well.
If a large percentage of the portfolio matures during the same quarter, the fund may depend on favorable refinancing markets at one specific moment. If banks suddenly tighten credit, multiple borrowers could request extensions simultaneously.
Staggered maturities allow capital to return gradually and give the manager repeated opportunities to adjust leverage, pricing, reserves, and loan terms as conditions change.
Diversification Cannot Repair Weak Underwriting
A portfolio of 100 poorly underwritten loans is not conservative simply because no single loan is very large.
If every loan was made at an aggressive LTV, depends on optimistic appreciation, or sits behind another lender, diversification may only spread the same weakness across more properties.
Loan-level discipline still comes first:
- Conservative leverage
- Strong collateral
- First-lien position
- Experienced borrowers
- Credible repayment plans
- Adequate reserves
- Enforceable documentation
Diversification becomes valuable after those standards have been satisfied.
What Investors Should Ask About The Loan Tape
An investor evaluating a private real estate credit fund should ask:
- What percentage of the fund is represented by its five largest loans?
- What is the maximum exposure to one borrower or sponsor?
- How concentrated is the portfolio by state and metropolitan area?
- What percentage is allocated to each property type?
- Are several loans dependent on the same guarantor or repayment source?
- How much of the portfolio matures within the same six-month period?
- Are concentration limits mandatory or discretionary?
- How would one significant default affect distributions and investor principal?
No fund can diversify away every risk. During a severe downturn, multiple property types and geographic markets may weaken together.
But a properly constructed loan tape can prevent an isolated mistake, borrower failure, or regional problem from threatening the entire portfolio.
The purpose of diversification is not to make every loan perform.
It is to make sure the fund does not require every loan to perform in order to protect investor capital.